Credit Score 750+: What Benefits Can You Get?
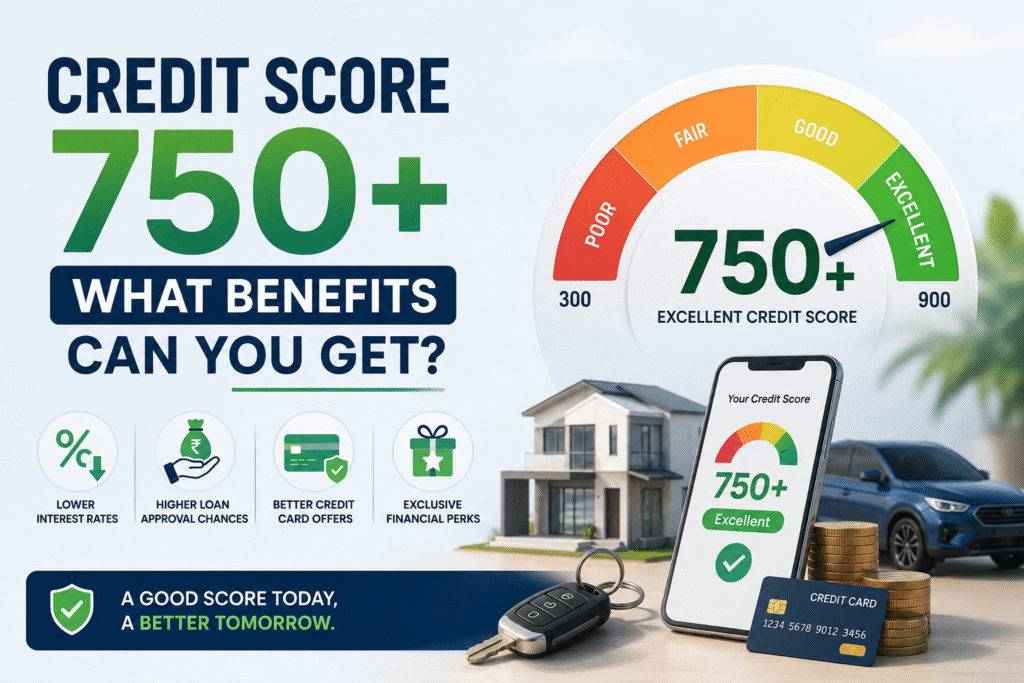
If you have checked your CIBIL score recently and seen a number above 750, you are sitting in a good spot. Most Indian banks and NBFCs treat 750 as the line that separates an average borrower from a preferred one, and crossing it changes how lenders deal with you, not just whether they say yes.
This article walks through what a 750+ credit score actually gets you in practical terms: lower interest rates, faster approvals, bigger credit limits, and access to loan products and cards that are simply out of reach for lower scores. We will also look at real numbers, since the difference between a 750 score and a 650 score is not academic, it shows up directly in your EMI.
What Does a 750+ Credit Score Mean?
Credit scores in India run on a scale of 300 to 900, and CIBIL, maintained by TransUnion CIBIL (Credit Information Bureau India Limited), remains the most widely used bureau score among lenders. Experian and Equifax also issue scores, and most platforms now report on the same 900-point scale for consistency.
Here is roughly how banks and NBFCs read the scale:
| Score Range | Category | What It Means for You |
|---|---|---|
| 800 – 900 | Excellent | Best available interest rates, instant pre-approved offers |
| 750 – 799 | Very Good | Top-tier loan deals, low rates, quick approvals |
| 700 – 749 | Good | Standard approval, competitive but not the lowest rates |
| 650 – 699 | Fair | Approval possible, often at higher rates or with conditions |
| Below 650 | Poor | Loans harder to get, higher rates, some rejections |
A score of 750 tells a lender that you have paid your dues on time, kept your credit utilisation in check, and managed a healthy mix of loans and cards over the years. Roughly 43% of credit-active Indians in metro cities now sit at 750 or above, so it is a real, achievable benchmark rather than a rare feat.
The Real Benefits of a 750+ Credit Score
1. Lower Interest Rates on Loans
This is the benefit that matters most to your wallet. Lenders price loans by risk, and a 750+ score puts you in the lowest risk bracket, which means you get the lowest advertised rate rather than a rate loaded with a risk premium.
Take home loans as an example. As of 2026, public sector banks in India are offering home loan rates starting around 7.10% to 7.50% per annum, while private banks such as HDFC Bank and ICICI Bank start a little higher. Almost every one of these starting rates is reserved for applicants with a CIBIL score of 750 and above. Fall below that threshold and the same bank may quote you a rate that is one to two percentage points higher.
The gap sounds small until you run the numbers on a real loan. On a home loan of ₹50 lakh over 20 years, moving from 8.5% to 7.1% brings your EMI down from roughly ₹43,391 to about ₹39,066, a saving of over ₹10 lakh across the loan tenure. That is not a rounding error; it is the price of a small car, paid entirely in interest you did not need to hand over.
The same principle holds for personal loans, car loans, and loans against property. A strong score does not just get you approved, it gets you approved cheaply.
2. Higher Chances of Approval
Below 750, lenders start asking more questions: proof of stable income, a co-applicant, extra collateral, or a lower loan amount than you asked for. Above 750, most of that friction disappears. Banks treat you as a low-risk profile and process the application on the strength of your credit history rather than layering on extra conditions.
This matters most when you need a loan quickly, whether that is a medical emergency, a business opportunity, or a property deal with a tight deadline. A 750+ score removes a lot of the back-and-forth that slows down approval for borderline applicants.
3. Faster Processing and Pre-Approved Offers
Many banks and NBFCs now run pre-approved loan and credit card offers based purely on your credit bureau data. If your score sits comfortably above 750, there is a decent chance you have already received an SMS or app notification offering you an instant personal loan or a credit limit increase without you asking for it.
Digital lenders in particular can turn around in-principle approval within 24 to 48 hours for strong profiles, compared to the usual week or two for average applicants. For salaried professionals juggling paperwork with a full-time job, this alone is worth chasing a good score.
4. Access to Premium Credit Cards
Credit card issuers reserve their best products, the ones with airport lounge access, higher cashback percentages, travel miles, and concierge services, for applicants above a certain score threshold, usually 750 or higher. A weaker score gets you a basic card with a modest limit; a strong score opens the door to cards that actually pay you back for your regular spending.
Card issuers also tend to offer higher initial credit limits to 750+ applicants, which itself feeds back into your credit utilisation ratio and helps your score stay healthy over time.
5. Better Negotiating Power
A high score is leverage. When your profile is strong, you are not simply accepting whatever rate a bank quotes; you can approach two or three lenders, compare offers, and ask your preferred bank to match or beat a competing quote. Banks would rather retain or win a low-risk customer than lose that business to a rival, so requests for a rate concession or a waived processing fee are far more likely to be heard when your score backs you up.
6. Lower Down Payment and Better Loan-to-Value Ratio
On secured loans such as home loans and car loans, your credit score can influence the loan-to-value (LTV) ratio a bank is willing to offer. A strong score sometimes means the bank is comfortable financing a slightly larger share of the property or vehicle value, which reduces the upfront amount you need to arrange from savings.
7. Waived or Reduced Processing Fees
Processing fees on loans typically range from 0.5% to 2% of the loan amount. Lenders occasionally waive or discount this fee during festive campaigns or as a relationship benefit, and applicants with scores above 750 are the ones most likely to be offered that discount, since the bank is competing to win their business.
How Much Can a 750+ Score Actually Save You?
Numbers make this easier to picture than percentages alone. Consider a ₹50 lakh home loan taken over 20 years.
- At 8.5% per annum, the EMI works out to roughly ₹43,391, with total interest paid over the tenure crossing ₹54 lakh.
- At 7.1% per annum, a rate realistically available to a 750+ borrower in 2026, the EMI drops to about ₹39,066, bringing total interest down by more than ₹10 lakh.
That gap alone could fund a child’s higher education or a healthy retirement top-up, simply from maintaining a good repayment record for a few years before applying.
How to Reach and Hold a 750+ Score
If you are not there yet, the path is fairly well established:
- Pay on time, every time. A single missed EMI or credit card due date does more damage than almost anything else on this list.
- Keep credit utilisation low. Using less than 30% of your total credit card limit at any point tends to work in your favour.
- Avoid applying for too much credit in a short span. Each hard inquiry causes a small, temporary dip.
- Maintain a healthy credit mix. A blend of secured loans, such as a home loan, and unsecured credit, such as a credit card, reflects well on your profile.
- Check your report regularly. Errors in your credit report, such as a loan that was closed but still shows as active, can drag your score down without you knowing. Most bureaus in India let you check your score for free once a year, and several apps offer free monthly checks.
Depending on your starting point, the climb to 750 can take anywhere from two to three months if you are already close, to well over a year if you are starting from a weak history. The timeline matters less than the consistency of the habits behind it.
Frequently Asked Questions
Is a 750 credit score good in India? Yes. Most Indian banks and NBFCs treat 750 as the threshold for their best loan rates and fastest approvals. Scores of 750 to 799 fall in the “very good” bracket, while 800 and above is considered excellent.
What is the minimum credit score needed for a home loan in India? Most lenders will consider applications from 650 upward, but the most competitive interest rates, generally in the 7.10% to 7.65% range as of 2026, are reserved for applicants with a score of 750 or higher.
Does a 750 credit score guarantee loan approval? No score guarantees approval on its own. Lenders also weigh income, existing obligations, employment stability, and the loan amount requested. A 750+ score significantly improves your odds and your pricing, but it works alongside these other factors.
How long does it take to reach a 750 credit score? It depends on your starting point. Someone already at 720 might cross 750 within two to three months of clean repayment behaviour. Someone starting from 650 may need six months to a year, and a climb from below 600 can take eighteen months to three years of consistent, disciplined credit use.
Can my credit score drop even if I have not missed a payment? Yes. Taking a new loan, closing an old credit account, or a sudden spike in credit utilisation can all cause a temporary dip, even without a missed payment. The score usually recovers once your credit behaviour stabilises.
Is CIBIL the only credit score used in India? No. CIBIL is the most widely used and recognised score among Indian lenders, but Experian and Equifax also issue credit scores, and most now report on the same 300 to 900 scale used by CIBIL.