Retirement Planning at 30, 40 and 50: What Changes?
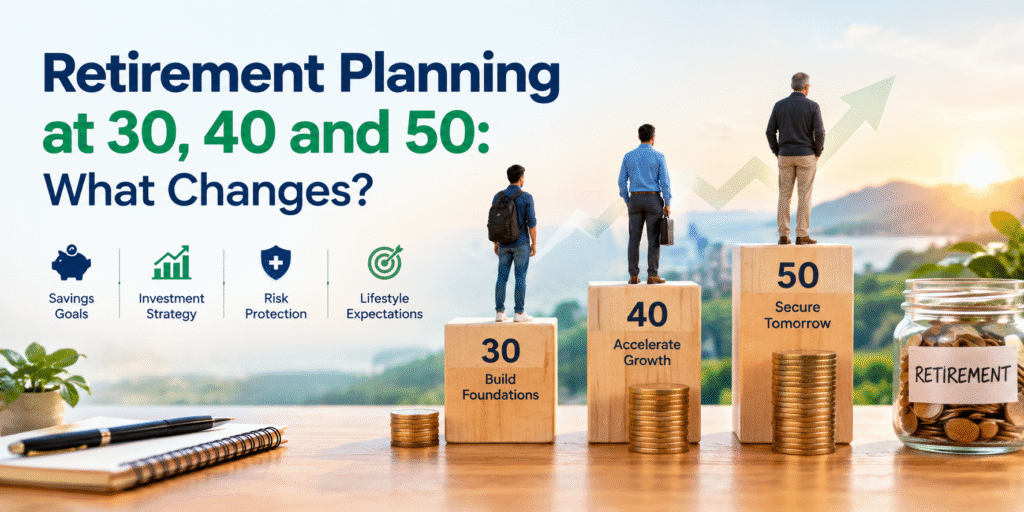
Most people treat retirement planning as one decision made early and left alone. Buy an NPS account, start an SIP, forget about it until the fifties. That approach quietly fails a lot of Indians, because the plan that works at 30 is not the plan that works at 50. What changes is not the goal. The goal stays the same: enough money to live on when the salary stops. What changes is the time you have left, the risk you can afford to carry, and how precisely you can now measure the gap between what you have and what you will need.
There is also a harder truth sitting underneath all of this. The EPFO pension under EPS caps out at roughly ₹7,500 a month, which will not cover rent in most Indian cities, let alone a full retirement. Whatever corpus you retire with, you are building almost all of it yourself, through EPF, NPS, PPF, mutual funds and whatever else you choose to hold. No employer and no government scheme is going to complete that job for you. So the decade you start taking this seriously matters more than most people realise.
Why Age Changes the Plan, Not the Goal
Three things shift as you move from 30 to 40 to 50.
Time. A rupee invested at 30 has thirty years to compound before retirement. The same rupee invested at 50 has ten. Compounding rewards time far more than it rewards the size of the monthly amount, which is why early starters build larger corpuses on smaller contributions.
Risk capacity. At 30, a market crash is a bump in a long road. At 50, a market crash close to retirement can permanently shrink the money you actually get to spend, because there is no time left to recover before you need to withdraw.
Certainty. At 30, retirement is an abstract number decades away. At 50, you can calculate your actual gap almost to the rupee, factoring in your real EPF balance, your real expenses, and your real retirement age. Planning stops being a guess and starts being arithmetic.
Everything below follows from these three shifts.
Retirement Planning at 30: Time Is the Whole Strategy
At 30, the single biggest lever you have is starting now rather than later. The numbers make this uncomfortably clear. A 25-year-old who invests ₹5,000 a month at an assumed 8% annual return builds close to ₹1.15 crore by age 60. Wait until 35 to start the same ₹5,000 a month, and the corpus falls to roughly ₹47.87 lakh, less than half, for the cost of just ten years of delay. That gap, over ₹67 lakh, is the price of procrastination, not the price of a smaller salary.
What this means practically for someone in their thirties:
- Let equity carry most of the weight. With thirty years to retirement, a portfolio tilted heavily toward equity mutual funds and index funds can absorb short-term volatility in exchange for long-term growth. Debt and fixed income can wait until later decades.
- Use EPF as the disciplined base, not the whole plan. If you are salaried at a company with 20 or more employees, EPF is mandatory, and your 12% contribution plus your employer’s share builds a tax-free, compounding base at a fixed rate of 8.25% for FY 2025-26. Do not withdraw it when you change jobs. Transfer it through the EPFO portal instead. Withdrawing EPF at every job switch is one of the most common ways young earners quietly shrink their own retirement corpus.
- Open an NPS account for the extra tax deduction. Beyond the regular Section 80C limit, NPS contributions under Section 80CCD(1B) allow an additional deduction of up to ₹50,000, on top of EPF and other 80C instruments.
- Buy term insurance now, while it is cheap. Life cover has nothing to do with retirement corpus directly, but premiums rise sharply with age, and a 30-year-old locks in a lifetime of low-cost protection that a 45-year-old cannot.
- Set the contribution to increase automatically. A step-up SIP, where the monthly amount rises 10% every year in line with your income, does more for the final corpus than almost any fund selection decision.
The mistake to avoid at 30 is not under-saving. It is treating retirement as something to think about later, once the salary is “better.” The salary is rarely the constraint. The habit is.
Retirement Planning at 40: Catching Up and Locking In Discipline
By 40, most people are earning more than they were at 30, but they also have more competing priorities: a home loan, children’s education, ageing parents. Retirement planning at this stage is less about aggressive growth and more about making sure nothing else quietly eats the retirement allocation.
Key shifts for the forties:
- Rebalance away from pure equity, gradually. With roughly twenty years left rather than thirty, a portfolio that is 100% equity is still reasonable, but this is the decade to start building in some debt exposure through PPF, EPF, or debt mutual funds, so a bad market year closer to retirement does not do as much damage.
- Check your NPS allocation, not just your NPS balance. NPS lets you choose your own split between equity, corporate debt and government securities. Many people set this once at account opening and never revisit it. Forty is a good age to review whether that original allocation still matches your risk appetite.
- Protect the corpus you have already built. This is the decade to increase health insurance cover, not decrease it. Premiums for a fresh health policy jump sharply after 55, so buying a higher cover, including a super top-up plan, in your forties locks in both lower premiums and continuity of coverage that will matter far more once you retire and lose any employer health cover.
- Do not let your child’s education fund and your retirement fund share the same account. This sounds obvious, but it is one of the most common mistakes at this age: parents redirect retirement SIPs toward education costs, assuming they will “catch up later” for retirement. Later rarely comes with the same force of habit as now.
- Run the actual numbers, not a rough guess. At 40, you have enough salary history and enough EPF and NPS statements to calculate a genuine retirement corpus target, factoring in your likely retirement age, current monthly expenses, and an inflation assumption of 6 to 7%. This is also the decade to price in healthcare inflation separately, since medical costs in India have been rising at 12 to 14% a year, well above general inflation.
If thirty is about starting, forty is about not letting the plan drift while life gets busier.
Retirement Planning at 50: From Growth to Protection and Precision
At 50, the maths changes completely. There are roughly ten years left before a typical retirement age, and a serious market downturn now has far less time to recover from before withdrawals begin. This is the decade where capital protection matters more than chasing returns, and where the plan needs to move from a general target to an exact number.
What changes at 50:
- Shift the balance toward debt and fixed income. Many financial planners in India suggest keeping no more than 30 to 40% of a retirement portfolio in equity by this stage, with the rest spread across PPF, EPF, NPS debt options, and instruments like the Senior Citizens’ Savings Scheme once eligible, which currently offers 8.2%.
- Understand the new NPS withdrawal rule. As of the 2026 update, NPS subscribers can withdraw up to 80% of their total corpus as a lump sum at retirement, up from the earlier 60%, with the remaining 20% used to purchase an annuity. Government employees follow a different split, generally able to withdraw up to 60% as lump sum with 40% going to annuity. Knowing this rule changes how much of your NPS corpus you can actually plan to use freely versus how much is locked into a pension income stream.
- Account for gratuity and leave encashment properly. Gratuity is tax-exempt up to ₹20 lakh, and this, along with leave encashment, forms a meaningful part of the retirement corpus for salaried employees that many people forget to include when calculating their total number.
- Price healthcare separately and seriously. At 14% medical inflation, healthcare costs at retirement can form a much larger share of monthly expenses than most people budget for. A dedicated healthcare buffer, kept separate from the general retirement corpus, matters more at 50 than at any earlier stage, since there is little time left to recover from an unplanned medical expense eating into invested capital.
- Decide on annuity versus systematic withdrawal now, not at the retirement date. A Systematic Withdrawal Plan from mutual funds and an annuity from NPS or an insurer solve the same problem, steady income after the salary stops, in very different ways. Annuities offer certainty but usually lower returns and are fully taxable. SWPs offer flexibility and potentially better returns but carry market risk. This decision needs research well before the last working year, not in the final weeks.
- Clear high-interest debt before it clears your corpus. Any personal loan or credit card debt carried into retirement draws down the corpus faster than almost anything else. Fifty is the decade to be debt-free, or very close to it, ahead of the actual retirement date.
Retirement Allocation by Decade: A Quick Reference
| Age Band | Primary Focus | Typical Equity Allocation | Key Instruments |
|---|---|---|---|
| Around 30 | Maximise growth, build the habit | 70 to 90% | Equity mutual funds, index funds, EPF, NPS, term insurance |
| Around 40 | Protect gains, plug leaks | 50 to 70% | EPF, NPS (reviewed allocation), PPF, health insurance, debt funds |
| Around 50 | Preserve capital, plan the exit | 30 to 40% | PPF, EPF, NPS debt options, SCSS, annuity planning, SWP setup |
These ranges are general starting points, not fixed rules. Personal circumstances, existing assets and retirement age all shift the exact numbers.
Mistakes That Show Up at Every Age
A few habits damage retirement planning regardless of decade. Withdrawing EPF at every job change resets compounding each time. Skipping health insurance because an employer provides cover leaves a gap the day that job ends. Treating retirement planning as a one-time decision rather than something reviewed every few years means allocations drift far from what actually suits the current age. And relying on EPS pension alone, assuming it will be “enough,” ignores that its maximum payout will not cover basic expenses in most Indian cities today.
Frequently Asked Questions
What is the ideal retirement corpus for a 30-year-old in India? There is no single number, since it depends on current expenses, expected retirement age and lifestyle. As a working method, many planners suggest targeting 25 to 30 times your expected annual expenses at retirement, adjusted for inflation. The more useful discipline at 30 is not fixing the final number but starting a consistent SIP and EPF contribution early, since time does more work than precision at this stage.
How much should I invest for retirement at 40? A common guideline is to save 20 to 25% of gross income toward retirement by the early forties, combining EPF, NPS and mutual fund SIPs. This is also the age to run an actual calculation using current EPF and NPS balances rather than relying on a general percentage.
Is NPS or EPF better for retirement planning after 50? They serve different purposes rather than competing directly. EPF offers a fixed, tax-free return of 8.25% for FY 2025-26 with no market risk, which suits capital protection closer to retirement. NPS offers market-linked growth along with an additional tax deduction under Section 80CCD(1B) and more withdrawal flexibility since the 2026 rule change. Most people nearing 50 benefit from holding both rather than choosing one over the other.
What is the new NPS withdrawal rule in 2026? Under the 2026 update, private sector NPS subscribers can withdraw up to 80% of their total corpus as a lump sum at retirement, with the remaining 20% mandatorily used to purchase an annuity. This is a change from the earlier 60% lump sum limit and gives retirees considerably more flexibility over how they use their NPS savings.
How much retirement corpus do I need in India? The realistic answer depends on your city, lifestyle and healthcare needs, but a useful starting method is to calculate your expected annual expenses at retirement, factor in inflation of 6 to 7% for general costs and 12 to 14% for healthcare separately, and multiply by the number of years you expect to live post-retirement, generally planning to age 85 for safety. Online retirement corpus calculators that include EPF, NPS and PPF together can give a closer estimate than a flat rule of thumb.
The One Thing That Does Not Change
Whatever decade you are reading this in, the underlying rule is unchanged. The EPFO pension will not be enough on its own. The corpus has to be built, mostly by you, across EPF, NPS, PPF and market-linked investments, with the mix shifting from growth toward protection as retirement gets closer. Thirty is for starting without excuses. Forty is for staying disciplined while life gets more expensive. Fifty is for turning a rough plan into an exact number and protecting it. Miss the decade you are in, and there is no fully making it up in the next one.