SIP vs FD vs Stocks: Where Should Beginners Invest?
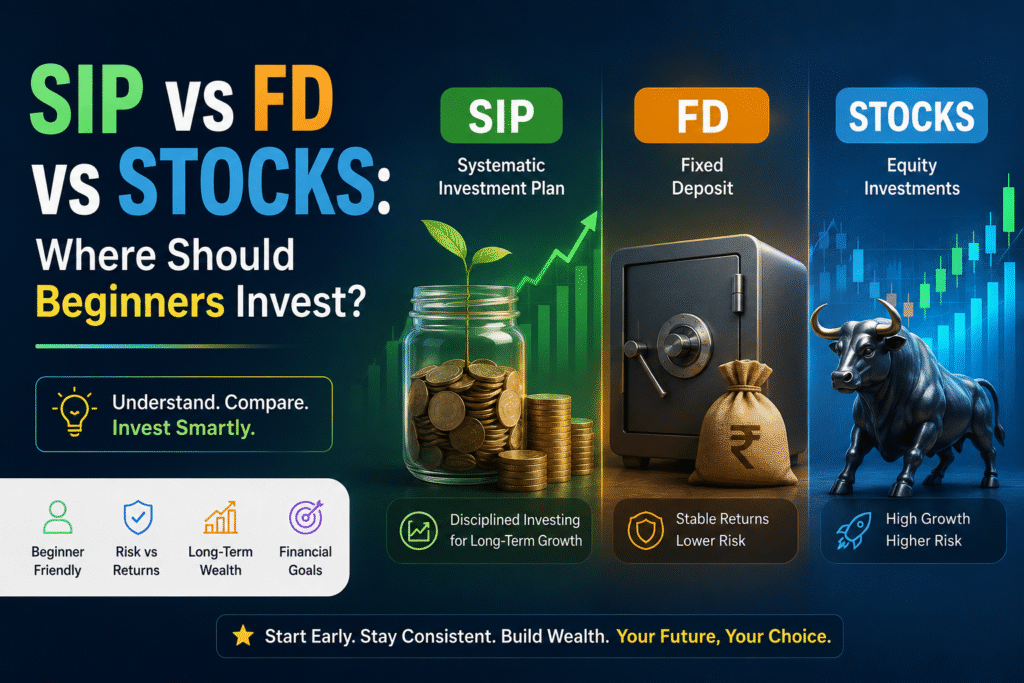
Every new investor in India asks the same question at some point. Should the first bit of savings go into a SIP, a fixed deposit, or straight into the stock market? The honest answer is that there is no single winner. Each option is built for a different job, and a beginner who understands what that job is will make a far better decision than one chasing whichever option a relative or a YouTube video praised last week.
This article walks through how SIPs, FDs and direct stock investing actually work, compares them on returns, risk, liquidity and tax, and ends with a practical way to split your money if you are just starting out.
What is a SIP?
A Systematic Investment Plan, or SIP, is simply a standing instruction to invest a fixed sum into a mutual fund every month. You can start with as little as ₹100 to ₹500, and the amount is auto-debited from your bank account on a date you choose. Over time, this small, repeated investment buys more units when the market is down and fewer units when the market is up. This averaging effect is called rupee cost averaging, and it removes the pressure of trying to time the market, which even full-time fund managers rarely get right.
SIPs are not a separate asset class on their own. They are a method of investing, and the underlying mutual fund can be an equity fund, a debt fund, or a hybrid fund. Most first-time SIP investors choose an equity or a hybrid fund because the goal is usually long-term wealth creation rather than short-term parking of money. According to AMFI data, more than 4.5 crore SIP accounts were active in India in early 2026, which shows how mainstream this method has become for salaried and self-employed investors alike.
What is a Fixed Deposit?
A Fixed Deposit, or FD, is a lump sum you hand over to a bank or NBFC for a fixed period, in exchange for a fixed rate of interest decided at the time of booking. There is no guessing involved. If a bank offers 7% for a three year FD, you know exactly what you will get at maturity, down to the rupee, assuming you do not break it early.
As of September 2026, FD rates from large public sector banks such as SBI hover between 6.4% and 6.5% for general depositors, while private banks like HDFC offer slightly higher rates in the range of 7% to 7.4% depending on tenure. Small finance banks push this further, with some offering 8% to as high as 9.35% on select tenures, though this comes with a marginally higher counterparty risk that most beginners overlook. Senior citizens typically get an extra 0.25% to 0.75% across the board.
FDs are the closest thing India has to a guaranteed return product, insured up to ₹5 lakh per depositor per bank under DICGC cover. This is exactly why FDs remain the backbone of Indian household savings, with total bank deposits crossing ₹200 lakh crore according to RBI figures.
What is Direct Stock Investing?
Buying stocks means you open a demat and trading account with a broker such as Zerodha, Groww or Upstox, and you personally choose which companies to invest in. Unlike a SIP into a mutual fund, where a fund manager makes the calls, direct stock investing puts the entire decision, and the entire risk, on you.
This is the option with the highest possible upside and also the highest possible downside. A stock can double in a year, or it can lose half its value on one bad quarterly result. Beginners often underestimate how much time and research this route demands, from reading balance sheets to understanding sector cycles to resisting the urge to sell in a panic during a correction.
SIP vs FD vs Stocks: Returns Compared
FDs offer certainty but not much growth. At current rates of around 6.5% to 7.5% from major banks, a ₹1 lakh FD grows to roughly ₹1.4 lakh in five years. That is a known, fixed number, and it barely beats inflation once you account for tax on the interest.
SIPs into equity mutual funds have no guaranteed number, but long periods of Indian equity market history show average annual returns in the range of 12% to 15%, though this varies widely depending on the years you invest in and the fund you choose. A SIP that runs through both a bull run and a market crash tends to smooth out the bumps far better than a lump sum investment made at the wrong time.
Direct stocks can outperform both of the above by a wide margin if you pick the right companies at the right price, but the same route can also underperform an FD if you pick the wrong ones or panic-sell during a downturn. There is no floor on stock returns the way there is on an FD.
SIP vs FD vs Stocks: Risk Compared
Risk is where these three options separate most clearly.
An FD carries almost no market risk. Your principal is safe, and the only real risks are inflation eating into real returns and, in rare cases, a small finance bank or NBFC running into trouble, which is why the ₹5 lakh DICGC insurance limit matters.
A SIP into an equity mutual fund carries market risk, since the value of your units moves with the stock market. But because a mutual fund holds dozens of stocks across sectors, the impact of any single company doing badly is diluted. Add rupee cost averaging on top of that, and the day-to-day volatility becomes far easier to sit through.
Direct stocks carry the highest concentration risk. If you hold five or ten stocks and one of them is hit by a scandal, a regulatory action or a sudden earnings miss, your portfolio can take a real hit that a diversified mutual fund would rarely experience in the same way.
SIP vs FD vs Stocks: Liquidity Compared
SIPs and the mutual fund units they build up are fairly liquid. You can redeem most open-ended equity funds within a few working days, though an exit load may apply if you sell within the first year.
FDs are technically liquid too, but breaking one early usually costs you a penalty of 0.5% to 1% on the interest rate, and in some cases you lose the higher rate you had locked in.
Stocks are the most liquid of the three during market hours. You can sell a listed stock and see the money in your account within a couple of working days, though selling in a panic during a crash is exactly the kind of liquidity that hurts your returns rather than helping them.
Tax Treatment of SIP, FD and Stocks
Tax rules affect your real, in-hand return, and this is a step beginners often skip.
FD interest is added to your total income and taxed at your income slab rate every year, whether you withdraw it or not. Banks deduct TDS if your interest income crosses the prescribed threshold in a financial year, and you can claim this back at the time of filing if your total tax liability is lower.
Gains from equity mutual funds and direct stocks are treated as capital gains. If you hold your units or shares for more than a year, the gain is treated as long-term and taxed at 12.5%, with the first ₹1.25 lakh of gains in a financial year exempt. If you sell within a year, it is treated as short-term and taxed at a flat rate, regardless of your income slab. This tax structure is one reason SIPs into equity funds often work out more tax-efficient than FDs for anyone in the higher income slabs, since a large part of FD interest can get taxed at 30% while long-term equity gains are taxed at 12.5%.
Which One Should a Beginner Choose?
There is no one-size answer here, but a few simple rules help most beginners decide.
If your goal is less than three years away, an FD or a recurring deposit makes more sense. You do not want your emergency fund, your wedding fund or your down payment sitting in the stock market where a sudden dip could force you to sell at the wrong time.
If your goal is five years or more away, a SIP into a diversified equity mutual fund is usually the better starting point for a beginner. It gives you market-linked growth without asking you to become a stock analyst overnight.
If you enjoy studying companies and can handle watching your money swing by 10% to 20% in a bad month, direct stocks can be added once you have a base built through SIPs and FDs. Very few financial advisors recommend starting your investing journey with direct stocks alone, because the learning curve is steep and mistakes made with your first savings are expensive lessons.
A Simple Way to Split Your Money as a Beginner
A pattern that works for a lot of first-time investors in India looks something like this. Keep three to six months of expenses in an FD or a liquid fund as a safety net. Once that cushion exists, start a SIP in a diversified equity or hybrid mutual fund for goals that are five years or more away, such as retirement or a child’s education. Only after these two are in place should you set aside a smaller portion, one you are genuinely comfortable losing without affecting your lifestyle, to learn direct stock investing.
This is not the only way to structure a portfolio, but it respects the basic order most people should follow: safety first, growth second, and speculation last.
Frequently Asked Questions
Is SIP better than FD for a beginner? For long-term goals, a SIP in an equity mutual fund usually has more growth potential than an FD. For short-term goals or money you cannot afford to lose, an FD remains the safer choice because the returns are fixed and guaranteed.
Can a beginner start investing directly in stocks? Yes, but most advisors suggest beginners first build a base through SIPs and FDs, then move a small, separate portion of savings into direct stocks once they understand how to read a company’s financials and can handle market swings.
How much money is needed to start a SIP in India? Many mutual funds allow SIPs starting from ₹100 to ₹500 a month, which makes this one of the most accessible ways for a beginner to enter the market without needing a large lump sum.
Are FD returns guaranteed in India? Yes, FD returns are fixed at the time of booking and do not change with market conditions. Deposits up to ₹5 lakh per bank are also insured under DICGC, which adds another layer of safety.
What is riskier, SIP or direct stocks? Direct stocks are riskier than a SIP into a mutual fund. A SIP spreads your money across many companies through the fund, while direct stock investing concentrates your risk in the few companies you personally pick.
Should a beginner invest in SIP, FD and stocks all together? Many financial planners recommend exactly this combination once you have moved past the very first stage of investing. FDs cover safety, SIPs cover long-term growth, and a small stock portfolio can be added later for those willing to take on extra risk and research.