
Strategic vs Tactical Asset Allocation: Managing Portfolios Across Market Regimes
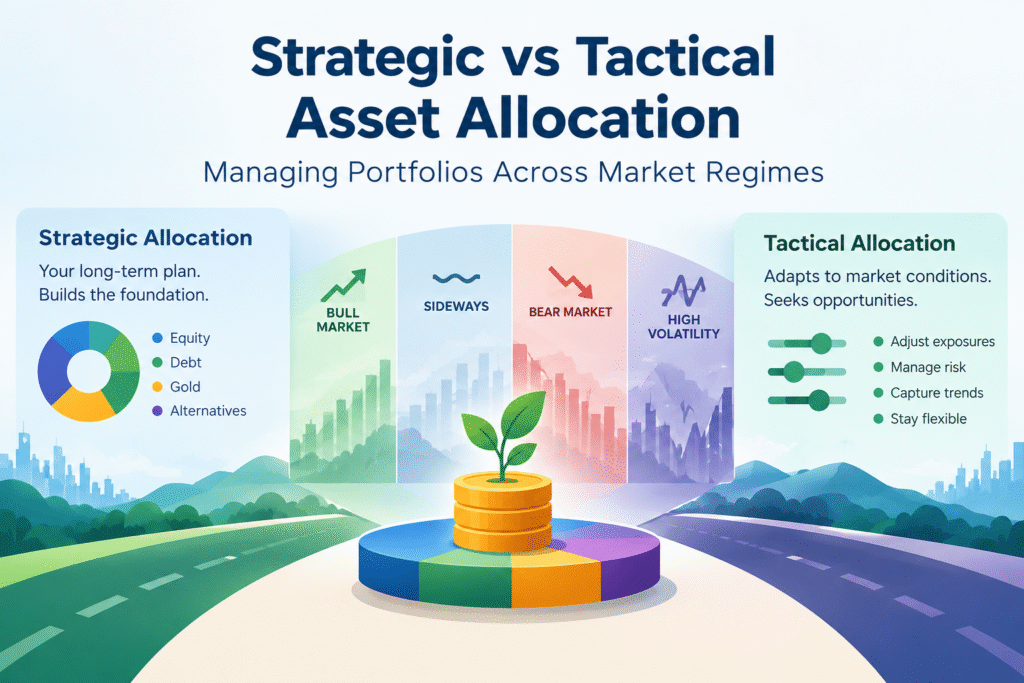
Most Indian investors spend weeks choosing a mutual fund and about five minutes deciding how much money should go into equity, debt and gold. That order is backwards. Studies going back to the 1980s, and the Brinson, Hood and Beebower paper is the one people usually quote, found that the split between asset classes explains most of the variation in a portfolio’s returns over time. The fund you pick inside each bucket matters much less.
So the real question is how you set that split and how you change it when markets change. Strategic and tactical asset allocation are the two approaches. This guide explains both, shows how they behave across market regimes, and gives a worked example in rupees.
Quick answer: Strategic asset allocation (SAA) is a long term target mix, for example 60% equity, 25% debt, 10% gold and 5% cash, set from your goals and risk tolerance and restored by rebalancing. Tactical asset allocation (TAA) is a short term, rule based move away from that mix to take advantage of a market condition, followed by a return to the target. SAA is the plan. TAA is a small, temporary change to the plan. Most retail investors do well with SAA as the base and, at most, a small capped tactical move.
What Is Strategic Asset Allocation?
Strategic asset allocation, also called policy asset allocation, is a fixed long term mix of asset classes. You decide the percentages once, based on three things: your investment horizon, your financial goals and how much loss you can live with, both financially and emotionally.
A 30 year old saving for retirement may hold 70% in equity, 20% in debt and 10% in gold. A 58 year old retiring in two years may hold 35% equity, 50% debt, 10% gold and 5% liquid funds. The method is the same: write the mix down and stick to it.
The strategy asks you to predict nothing. Prices will push the mix off target, so you rebalance. When equity rallies and grows beyond its share, you trim it. When it falls, you top it up. Rebalancing makes you sell some of what has become expensive and buy some of what has become cheap, which is hard to do by instinct.
What Is Tactical Asset Allocation?
Tactical asset allocation is an active strategy. You keep a strategic mix as your home base, and you move away from it for a limited period when you believe one asset class is more attractive or more risky than usual. Some writers call this dynamic asset allocation, though that term is also used for funds that shift their equity level by formula.
The signals vary. Some investors use valuations such as the Nifty 50 price to earnings ratio. Others use momentum, interest rate direction, inflation data or currency trends. The signal matters less than the discipline around it. Tactical investing is a form of market timing, so it demands real expertise, and the investor has to spot when the opportunity is over and move back to the long term mix without delay.
A tactical move needs two correct decisions, one to leave the base mix and one to return. Being right on the first and late on the second can wipe out the gain.
Strategic vs Tactical Asset Allocation: Key Differences
| Factor | Strategic asset allocation | Tactical asset allocation |
|---|---|---|
| Time horizon | Long term, 5 to 30 years | Short term, weeks to about 18 months |
| Basis for decisions | Goals, horizon, risk tolerance | Market conditions, valuations, economic data |
| Portfolio changes | Rebalancing back to fixed targets | Deliberate deviation from targets |
| Trading frequency | Low, once or twice a year | Higher, depends on signals |
| Costs and tax | Low | Higher, from exit loads, spreads and capital gains tax |
| Skill needed | Basic discipline | Analysis and a written exit rule |
| Main risk | Rigid mix in a changed world | Wrong timing, overtrading |
| Suits | Most long term investors | Experienced investors with a small satellite portion |
What Are Market Regimes and Why Do They Matter?
A market regime is a stretch of time in which the economy and markets behave in a fairly consistent way. Growth and inflation do most of the work in defining it, with interest rates and volatility adding detail. A simple four box view is enough for most investors.
| Regime | Usually does well | Usually struggles | Strategic response | Possible tactical response |
|---|---|---|---|---|
| Growth up, inflation low | Equity, especially mid and small caps | Cash | Hold the mix, rebalance | Modest overweight to equity |
| Growth up, inflation high | Equity of pricing power businesses, gold, commodities | Long duration bonds | Hold the mix, rebalance | Shorter duration debt, a little more gold |
| Growth down, inflation low | Government bonds, gilt funds | Equity, credit risk debt | Hold the mix, rebalance | Longer duration debt for a while |
| Growth down, inflation high (stagflation) | Gold, cash, short duration debt | Both equity and long bonds | Hold the mix, rebalance | Trim equity slightly, raise short duration debt and gold |
No regime lasts forever, and the labels are clear only after the fact. That is the honest weakness of tactical investing: you have to identify the regime while it is still forming.
Where Indian Markets Stand Right Now
A snapshot as on 30 September 2026 shows why the debate is live. The Nifty 50 closed at 22,620.45, about 14.2% below its 52 week high and down about 8.1% over one year. On the rate side, the RBI’s Monetary Policy Committee held the repo rate at 5.25% in August 2026, its fourth straight pause, with a neutral stance. The central bank also projected 6.7% GDP growth and 5.0% CPI inflation for FY27. The 10 year government bond yield was about 6.84% in early August. Meanwhile the rupee traded near 95.83 to the US dollar and gold stood around $4,240 an ounce.
Read together, that points to slowdown risk with inflation pressure, roughly the third and fourth boxes in the table above. A strategic investor checks whether the mix has drifted and does nothing else. A tactical investor may trim a little equity or hold more short duration debt. Both are reasonable. Selling everything because the Nifty fell for a few weeks, with no rule for buying back, is not.
A Worked Example: ₹10 Lakh Portfolio
Take an investor with a moderate risk profile and a 10 year horizon. The strategic mix is:
- Equity 60%, ₹6,00,000 (a Nifty 50 index fund and a flexi cap fund)
- Debt 25%, ₹2,50,000 (short duration and gilt funds, plus PPF)
- Gold 10%, ₹1,00,000 (gold ETF)
- Liquid funds 5%, ₹50,000
Strategic rebalancing. Suppose equity rises 25% in a year while everything else stays flat. Equity becomes ₹7,50,000 out of a portfolio of ₹11,50,000, which is 65.2%. The investor set a rule of rebalancing when any asset drifts more than 5 percentage points, so the rule triggers. Moving equity back to 60% means selling about ₹60,000 of equity and adding it to debt, gold and liquid funds in line with their targets. No forecast was needed.
Tactical tilt. Now suppose the investor allows a tactical band of 5 percentage points around equity, so equity can sit anywhere from 55% to 65%. With inflation pressure building, they cut equity to 55% for about six months and hold the extra ₹50,000 in a short duration debt fund. The cost matters here. Selling equity or equity funds inside a year costs a flat 20% tax on the gain, and after a year the rate is 12.5% on gains above ₹1.25 lakh in a financial year. If the units sold carry a ₹5,000 gain and were held under a year, the tax is ₹1,000 plus 4% cess, so ₹1,040. That is about 2% of the money moved, before any exit load. The tilt has to be worth more than that to make sense. The debt side is not tax free either, because gains on debt funds bought after 1 April 2023 are added to your income and taxed at your slab rate.
Put plainly, rebalancing is cheap and needs no opinion. A tactical move costs money and needs an opinion that turns out right twice.
Rules for Tactical Moves, If You Use Them
A few written rules keep tactical asset allocation in check.
- Cap the size. Limit any tilt to 5 to 10 percentage points and limit the total tactical portion of the portfolio.
- Write the trigger. For example, “reduce equity by 5 points if the Nifty 50 price to earnings ratio stays above a level I have chosen for three months.” A trigger written in advance stops decisions made in panic.
- Write the exit. Decide the condition and the date on which you return to the strategic mix, before you make the move.
- Count the cost. Add up exit load, tax and spread. If the expected gain is not clearly larger, skip the move.
- Use new money first. Pointing your monthly SIP at the underweight asset changes the mix without selling.
Core and Satellite: Combining Both Approaches
The most practical structure for a retail investor is a core and satellite portfolio. About 80% to 90% of the money sits in the strategic core, managed by rebalancing. The remaining 10% to 20% is the tactical satellite, where you act on your regime views. If a tactical call goes wrong, the damage stays in the satellite.
Ready Made Options in India
If you want some tactical behaviour without running it yourself, two mutual fund categories exist for that purpose.
Balanced advantage funds move between equity and debt based on the fund house’s model, usually valuation based. You hand the tactical decision to the fund manager. Some fund houses describe this style as a core and tactical mix, blending a long term base with shorter term shifts. Check the factsheet for the equity percentage, because it decides how the fund is taxed.
Multi asset allocation funds hold at least three asset classes, typically equity, debt and gold, with a minimum of 10% in each under SEBI rules. They give you a strategic mix in one fund, with some manager discretion on top.
Both cost more than plain index funds, so compare expense ratios and long term records, not last year’s returns.
Which Approach Suits You?
Choose strategic asset allocation if you invest through SIPs, have long term goals such as retirement or a child’s education, and tend to panic in falling markets.
Add a small tactical satellite if you have seen at least one full market cycle, can write your rules down, and accept that some moves will be wrong.
Use a balanced advantage or multi asset fund if you want automatic shifts and do not want to decide them yourself.
Common Mistakes to Avoid
- Changing the strategic mix after a fall. If your risk tolerance really changed, revise the plan on a calm day, not during a crash.
- No exit rule. Many tactical moves become permanent because there was no condition to reverse them.
- Mixing up regimes and headlines. One bad week is not a change of regime.
Frequently Asked Questions
What is the difference between strategic and tactical asset allocation?
Strategic asset allocation sets a fixed long term mix of equity, debt, gold and cash based on your goals and risk tolerance, and brings the portfolio back to that mix through rebalancing. Tactical asset allocation temporarily moves away from that mix to take advantage of short term market conditions, then returns to the target.
Which is better for Indian investors, strategic or tactical asset allocation?
For most retail investors, strategic asset allocation is the better base because it is cheaper, simpler and needs no forecasting. Tactical asset allocation can add a small satellite for experienced investors, at the price of extra tax, cost and timing risk.
Can I use strategic and tactical asset allocation together?
Yes. A core and satellite structure keeps 80% to 90% of the portfolio in a strategic mix and uses the remaining 10% to 20% for tactical views. Any tactical loss is then limited to the satellite portion.
How often should I rebalance my portfolio?
Once or twice a year is enough for most investors, or whenever an asset class drifts more than 5 percentage points from its target. Directing new SIP money to the underweight asset class can reduce the need to sell.
What is a market regime?
A market regime is a period in which growth, inflation, interest rates and volatility combine to produce a fairly consistent pattern of returns, such as a low inflation growth phase, a slowdown or stagflation. Regimes are usually clear only in hindsight.
Does tactical asset allocation beat strategic asset allocation?
The evidence is mixed. Tactical strategies can add value when the timing is right, but they carry higher costs and must be right on both the exit and the return. Many investors find a disciplined strategic mix performs as well after costs and tax.
Are balanced advantage funds a form of tactical asset allocation?
Yes, in effect. These funds change their equity and debt weights within a range based on a model, so the manager makes the tactical decision on your behalf. Check the equity percentage in the factsheet, since it decides whether the fund is taxed as an equity fund or under other rules.
What are the tax implications of changing my asset allocation in India?
Selling units to change your mix is a taxable event. Equity fund gains within 12 months are taxed at 20%, and gains beyond ₹1.25 lakh a year after 12 months at 12.5%. Debt funds bought after 1 April 2023 are taxed at your slab rate. Rebalancing with fresh money avoids most of this.
Final Thoughts
Strategic asset allocation gives you a plan you can follow when markets are calm and when they are not. Tactical asset allocation gives you room to act on a view, at a price. For most people the sensible order is to set the strategic mix first, rebalance on a schedule, and only then decide whether a small tactical portion is worth the trouble. A plan written in advance will serve you better than a decision made in the middle of a market regime.
This article is for education only and is not investment advice. Please check your own risk profile, or speak to a SEBI registered investment adviser, before you change your portfolio. Market figures are as on 30 September 2026 and will change.