
Core-Satellite Portfolio Construction: Combining Passive and Active Strategies
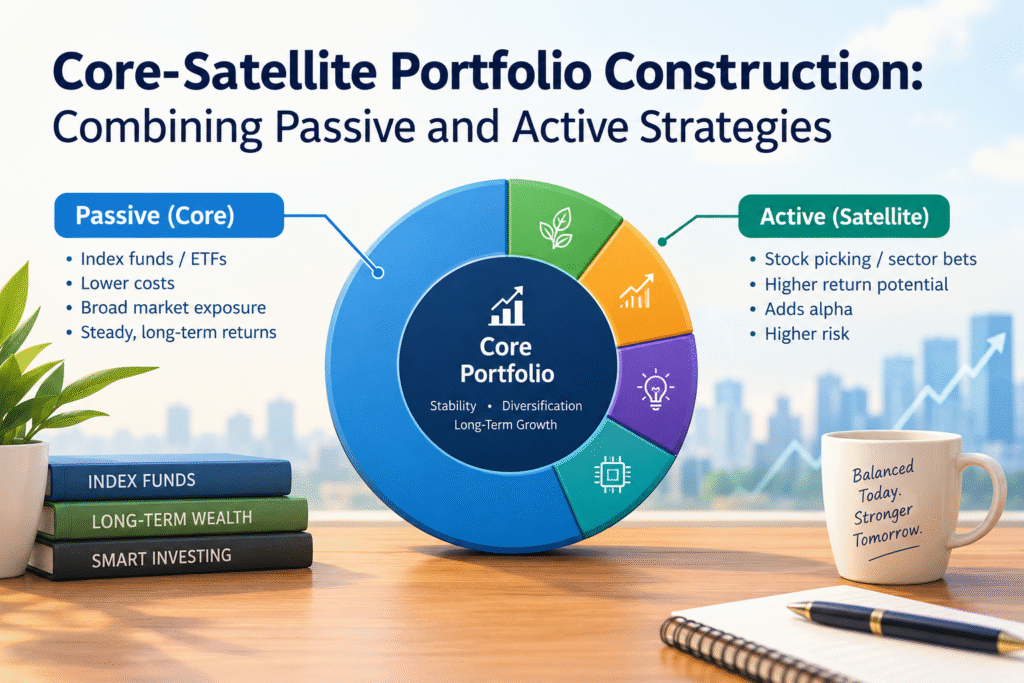
Quick answer: A core-satellite portfolio keeps most of your money in low-cost, passive investments such as Nifty 50 index funds, and uses a smaller slice for active bets such as mid-cap funds, sector funds, international funds, or direct stocks. In India, the core usually holds 60 to 80% of the investments, while the satellite portion holds 20 to 40%. The core gives you market returns at low cost. The satellite gives you a chance to earn more, without letting one wrong call damage your whole plan.
If you have ever sat between two camps, one saying “just buy an index fund” and the other saying “good fund managers beat the market”, this strategy is for you. It does not ask you to pick a side. It gives each approach a job.
What Is a Core-Satellite Portfolio?
Core and satellite investing splits your portfolio into two parts with different purposes.
The core is the foundation. It holds broad, diversified, low-cost investments that you plan to keep for many years. Think index funds, large-cap funds, and debt instruments like PPF or short-duration bond funds. You do not trade the core often.
The satellite is the smaller, more flexible part. It holds investments where you are trying to beat the market, which in finance terms means earning alpha. Satellites can be actively managed mutual funds, thematic funds, international funds, gold, or a few individual stocks.
The name comes from the picture it paints. The core is the planet, and the satellites move around it. If a satellite fails, the planet is still there.
Professional fund managers and wealth advisors have used this structure for decades. It works just as well for a retail investor with a monthly SIP of ₹10,000 as it does for a large family office.
Why Combine Passive and Active Investing?
Both styles have real strengths, and both have real weaknesses.
Passive investing means buying a fund that copies an index, such as the Nifty 50 or the Sensex. The fund does not try to pick winners. Costs are low, there is no dependence on a fund manager’s skill, and you get the market return minus a small fee.
Active investing means a fund manager picks stocks to try to beat the index. You pay a higher expense ratio for that effort. Sometimes it pays off. Often it does not.
The numbers are worth looking at. According to the SPIVA India scorecard from S&P Dow Jones Indices, 73% of Indian large-cap funds and 82% of mid-cap and small-cap funds underperformed their benchmarks over the past 10 years. For large caps, that is a strong argument for putting your core in an index fund.
The same data also shows why you should not write off active funds completely. On a risk-adjusted basis, only 48% of mid and small-cap funds underperformed over 10 years, and just 24% over 5 years. In the less crowded parts of the market, a good manager has more room to add value. That is exactly where a satellite belongs.
A word of caution on these figures. SPIVA results change with the benchmark used and the period chosen, so read them as a direction and not as a final verdict. The direction is clear enough, though. Pay low fees for the part of the market that is hard to beat, and spend your active effort where it has a better chance.
What Goes in the Core
The core should be boring, and that is a compliment. Its job is to capture the growth of the Indian economy at the lowest cost, and to keep your portfolio steady when the satellites misbehave.
Common core holdings for Indian investors:
- Nifty 50 or Sensex index funds and ETFs. These track broad market indices like the Nifty 50 or Sensex and are the usual first choice.
- Broad-market index funds, such as a Nifty 500 index fund, for exposure beyond the top 50 companies.
- Large-cap and flexi-cap funds, if you prefer a little active management in the core.
- Debt investments such as PPF, EPF, government bonds, or short-term debt funds, which add stability.
When you pick a core fund, check three things. First, the expense ratio. Lower is better, and you should choose the direct plan over the regular plan. Second, the tracking error, which tells you how closely the fund follows its index. Third, the fund’s size and track record. Two or three core funds are plenty. Owning seven index funds that all hold the same top 50 stocks adds paperwork, not diversification.
What Goes in the Satellite
The satellite is where you take calculated risks. Each satellite should have a clear reason to exist. If you cannot explain in one sentence why you own it, it probably does not belong.
Typical satellite choices in India:
- Mid-cap and small-cap mutual funds. These funds invest in growing companies that can offer high returns. They also fall harder in bad years.
- Sectoral and thematic funds, such as IT, pharma, infrastructure, or manufacturing funds.
- International funds, which add exposure to the US or other markets and reduce your dependence on India alone.
- Gold, through a gold ETF or sovereign-style gold products, as a hedge.
- Direct stocks, if you have the time and the temperament to research companies.
Keep the number of satellites small. One guide suggests introducing 2 to 4 satellite funds, and capping each at 5 to 10% of the total portfolio to prevent concentration risk. That is sound advice. Ten satellites each holding 3% is not a strategy, it is clutter.
How Much Should You Put in Core and Satellite?
There is no single correct split. Your age, income stability, goals, and how you react to a falling market all matter. Here is a simple starting framework, built from commonly used ranges:
| Investor profile | Core : Satellite | What it suggests |
|---|---|---|
| Young investor, stable income, long horizon | 60:40 or 70:30 | More room for satellite risk |
| Mid-career, family responsibilities | 75:25 or 80:20 | Balanced growth and safety |
| Close to retirement | 80:20 or 85:15 | Protect what you have built |
These ratios follow the ranges in a life-stage guide that suggests 60:40 or 70:30 for younger investors, 75:25 or 80:20 for mid-career, and 85:15 or 80:20 for those near retirement.
One more point. A 50:50 split sounds balanced but is risky. If all your satellites fall together, as they tend to do in a crash, a portfolio with 50% core and 50% satellite can fall 40 to 50%. Most people cannot sit through that without selling. A larger core protects you from your own panic.
A Worked Example: ₹10 Lakh Core-Satellite Portfolio
This is an illustration, not a recommendation. Fund names are left out on purpose, because the right fund depends on current costs and your own situation.
Assume a 35-year-old investor with a ₹10 lakh portfolio and a 70:30 split.
| Bucket | Investment | Allocation | Amount |
|---|---|---|---|
| Core | Nifty 50 index fund (direct plan) | 40% | ₹4,00,000 |
| Core | Nifty 500 index fund | 15% | ₹1,50,000 |
| Core | PPF or short-duration debt fund | 15% | ₹1,50,000 |
| Satellite | Actively managed mid-cap fund | 10% | ₹1,00,000 |
| Satellite | Small-cap fund | 5% | ₹50,000 |
| Satellite | International fund | 5% | ₹50,000 |
| Satellite | Gold ETF | 5% | ₹50,000 |
| Satellite | Direct stocks (2 to 3 companies) | 5% | ₹50,000 |
Notice the shape of it. The core is 70% and uses only three holdings. The satellite is 30% but is spread over five ideas, none above 10%. If the small-cap fund drops 30% in a bad year, the whole portfolio falls by only 1.5% from that holding alone. That is the point of the structure.
If you invest through a SIP, send the monthly amount to the same mix. A ₹30,000 monthly SIP would put ₹21,000 into the core and ₹9,000 into the satellites.
How to Build a Core-Satellite Portfolio, Step by Step
- Write down your goals. Retirement, a house, a child’s education. Each goal has a different time frame, and the time frame decides how much risk you can take.
- Decide your total equity and debt mix first. Core-satellite sits on top of your asset allocation. It does not replace it.
- Build the core first. Choose two or three low-cost funds and start the SIPs. Do this before you even look at satellites.
- Add satellites one at a time. Give each one a purpose and a size limit.
- Check for overlap. Many mid-cap and flexi-cap funds hold the same stocks as your index fund. Look at the top 10 holdings of each fund.
- Write your rules down. Note your target split, your rebalancing trigger, and when you would sell a satellite. Rules written in calm times are easier to follow in a panic.
Rebalancing Your Core-Satellite Portfolio
Over time, winners grow and losers shrink, so your 70:30 split will drift to 62:38 or 78:22. Rebalancing brings it back. The strategy is not a set-and-forget approach, and this is the main reason.
Two simple methods work well:
- Calendar rebalancing. Review once a year, on a fixed date such as your birthday or the start of the financial year.
- Band rebalancing. Act when any holding drifts more than 5 percentage points from its target.
Pick one and stick to it. Checking daily only leads to bad decisions.
The cheapest way to rebalance is with new money. Direct your fresh SIP amounts to whichever bucket is below target, and you may not need to sell anything at all.
Tax Effects of Rebalancing in India
Selling to rebalance can trigger capital gains tax, so plan for it. For equity mutual funds in FY 2026-27, short-term gains on units sold within 12 months are taxed at 20%, and long-term gains above ₹1.25 lakh in a financial year are taxed at 12.5%.
The ₹1.25 lakh exemption is shared across all your equity holdings. It applies to stocks, equity mutual funds, and business trusts combined, so you cannot claim it separately for each.
A quick example. Say you book ₹2 lakh of long-term gains in a year. After the ₹1.25 lakh exemption, ₹75,000 is taxable at 12.5%, which comes to ₹9,375 plus 4% cess, or ₹9,750 in total. Had those gains been short-term, the tax on ₹2 lakh would have been ₹40,000 before cess.
Practical tips:
- Rebalance with new SIP money first.
- If you must sell, sell units held for more than 12 months.
- Spread large redemptions over two financial years to use the exemption twice.
- Debt fund gains are taxed at your slab rate, with no such exemption, so remember that when you trim debt.
Tax rules change from time to time, so confirm the current rates before you act, or speak to a chartered accountant.
Common Mistakes to Avoid
Having too many satellites. More funds do not mean more diversification. They usually mean more overlap and higher costs.
Letting the satellite grow into the core. A hot mid-cap fund can swell to 20% of your portfolio in two good years. Rebalancing exists to stop this.
Chasing last year’s best performer. Past returns do not repeat on schedule. Fund rankings shuffle every year.
Ignoring costs. A 1% difference in annual expense ratio compounds into a large gap over 20 years. Always choose direct plans where you can.
Using the satellite for money you need soon. Satellite money should be money you can afford to see fall by half without changing your life.
Skipping the review. A plan that is never reviewed turns into a pile of old decisions.
Who Should Use a Core-Satellite Strategy?
This approach suits investors who want index fund simplicity but also want some room to try for higher returns. It is also a good fit for people who have seen themselves chase tips and want a structure that limits the damage.
It is a beginner-friendly method, too. A new investor can start with only a Nifty 50 index fund as the core and add a single satellite fund after a year or two, once the habit of investing is in place.
You may not need satellites at all if you have no interest in tracking funds. A plain portfolio of two or three index funds and a debt allocation is a perfectly good plan. Satellites are optional. The core is not.
Frequently Asked Questions
What is a core-satellite portfolio?
A core-satellite portfolio is an investment approach that splits your money into two parts. The core holds low-cost, diversified, long-term investments such as index funds. The satellite holds smaller, higher-risk investments such as mid-cap funds, sector funds, or direct stocks, aimed at earning extra returns.
What is a good core-satellite ratio for Indian investors?
Most guides suggest 60 to 80% in the core and 20 to 40% in the satellite. Younger investors with long horizons can lean toward 60:40 or 70:30. Investors close to retirement usually prefer 80:20 or 85:15.
Which funds are best for the core portfolio?
Nifty 50 and Sensex index funds, broad-market index funds such as Nifty 500, large-cap or flexi-cap funds, and stable debt options like PPF or short-duration debt funds are the usual picks. Look for a low expense ratio and low tracking error.
Which funds are best for the satellite portfolio?
Mid-cap funds, small-cap funds, sectoral and thematic funds, international funds, gold ETFs, and a few direct stocks are common satellite choices. Limit each one to roughly 5 to 10% of the total portfolio.
How often should I rebalance a core-satellite portfolio?
Once a year works for most investors. You can also rebalance whenever a holding drifts about 5 percentage points away from its target. Using new SIP money to correct the balance keeps tax costs low.
Is a core-satellite strategy better than only investing in index funds?
Not always. It depends on whether you are willing to research funds and accept extra risk. An all-index portfolio is simpler and cheaper. Core-satellite adds a controlled amount of active risk for investors who want it.
Does core-satellite investing work for SIP investors?
Yes. You can split each monthly SIP between core and satellite funds in your target ratio. Over time, redirect new SIP amounts to whichever bucket has fallen below its target.
How many satellite funds should I hold?
Two to four is enough for most investors. More than that usually creates overlap and makes the portfolio harder to track.
Final Thoughts
Core-satellite portfolio construction is a practical answer to the passive versus active debate. Put the bulk of your money where low cost matters most. Give a smaller share to ideas you believe in. Write down your rules, review once a year, and rebalance with new money when you can.
You do not need to get every satellite right. You only need a core strong enough that a few mistakes do not matter.
Disclaimer: This article is for general education and is not investment, tax, or legal advice. Mutual fund investments are subject to market risks. Please read all scheme documents carefully, and consult a SEBI-registered investment advisor or a chartered accountant before making decisions.